Stocks bounced to close the week, with the Nasdaq jumping 1.2% on Friday and finishing the week up 0.5%. It wasn’t a clean sweep. The S&P 500 slipped 0.2% on the week, and the Dow fell 1.3%. But with the 10-year Treasury yield climbing to its highest level since 2002, stocks even holding up this well says a lot. A much-softer-than-expected jobs report on Friday gave stocks a lift, and both the S&P 500 and Nasdaq finished the week within about 1% of their all-time highs. That’s not a bad setup, with what has historically been the best part of the year now here.
Payrolls disappoint by just the right amount
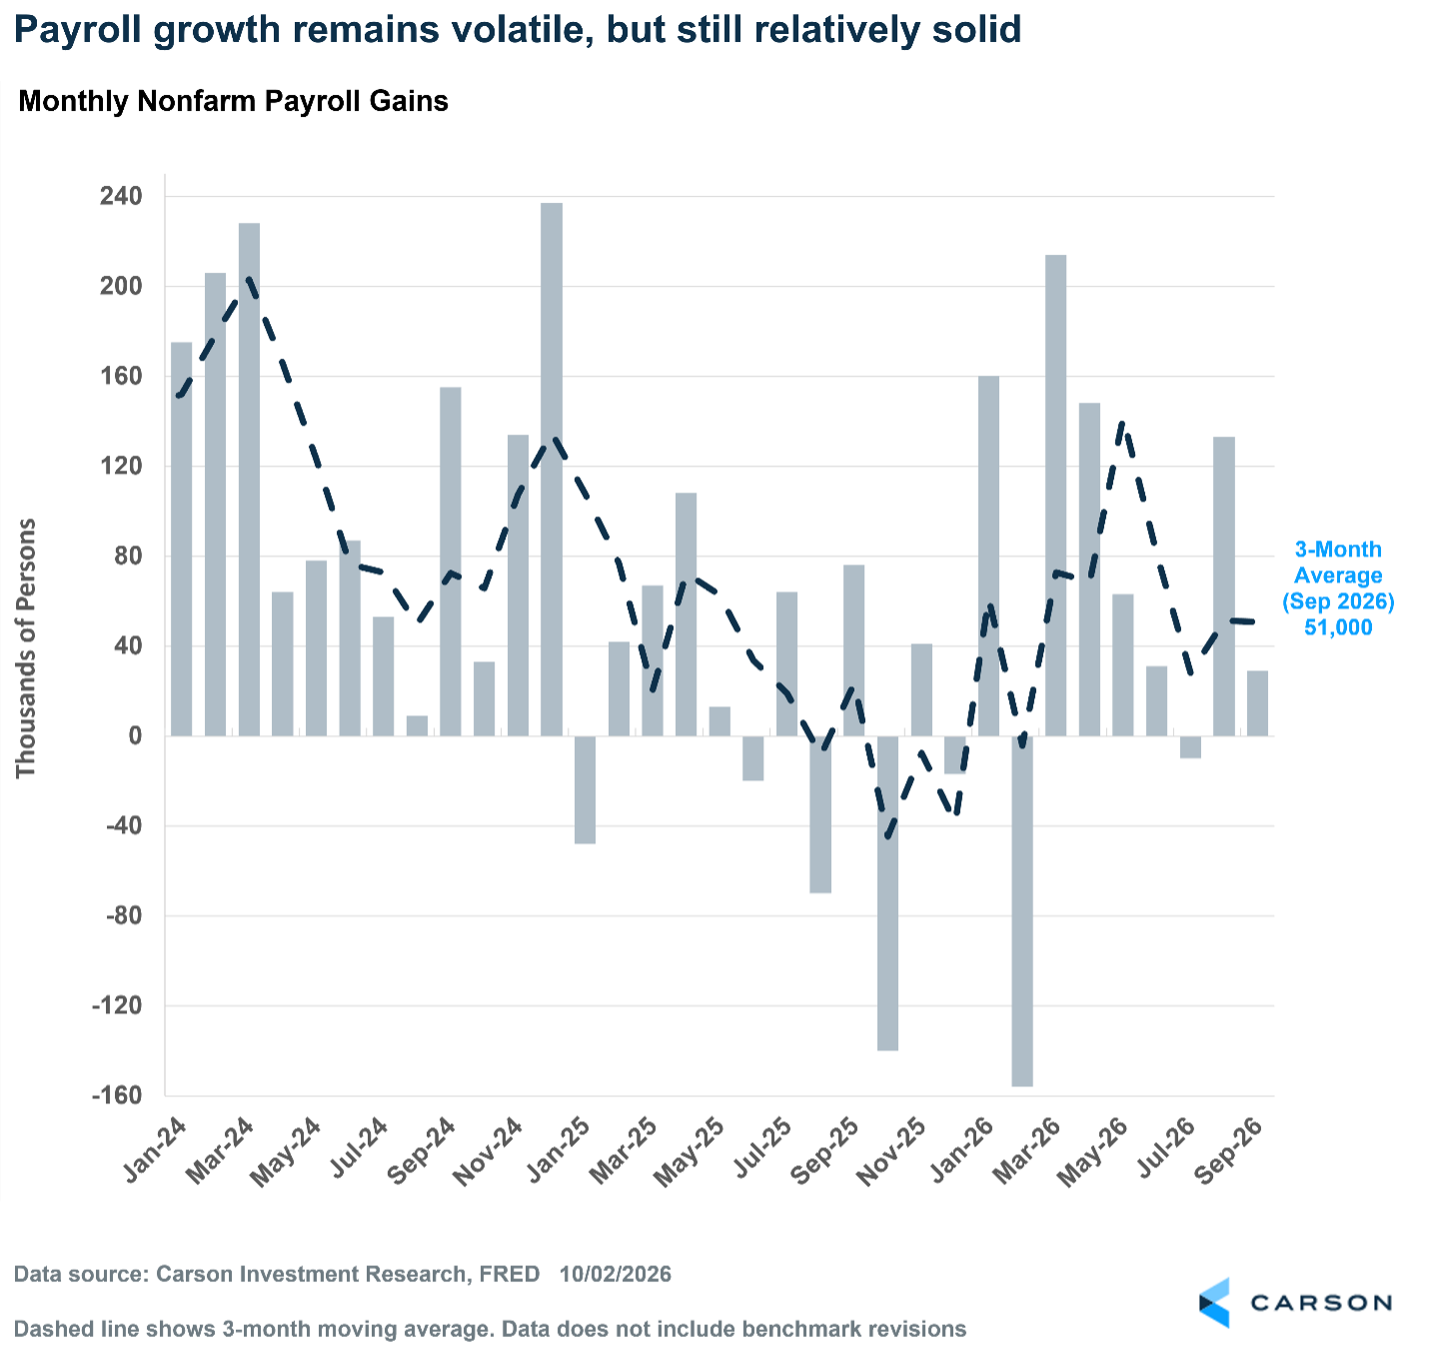
Headline payroll growth disappointed again in September, with the economy adding just 29,000 jobs, according to the report released Friday, October 2. That was well below expectations for a 90,000 gain.
We also got downward revisions: August was revised from +162,000 to +133,000, and July from +21,000 to -10,000. Put together, employment in July and August was 60,000 lower than previously reported, and the three-month average of job growth is down to 51,000 (from 71,000 last month).
Volatile payrolls are not abnormal
But this is not abnormal. Headline payrolls are volatile right now because labor supply is low, largely due to changes in immigration. Breakeven employment, which is the number of jobs the economy needs to create to keep up with population growth, is only around 25,000 a month. On top of that, the payroll survey has a 90% confidence interval of about plus or minus 120,000 jobs. That means we could very easily get months with negative payroll growth (like July) and some with more than 100,000 (like August).
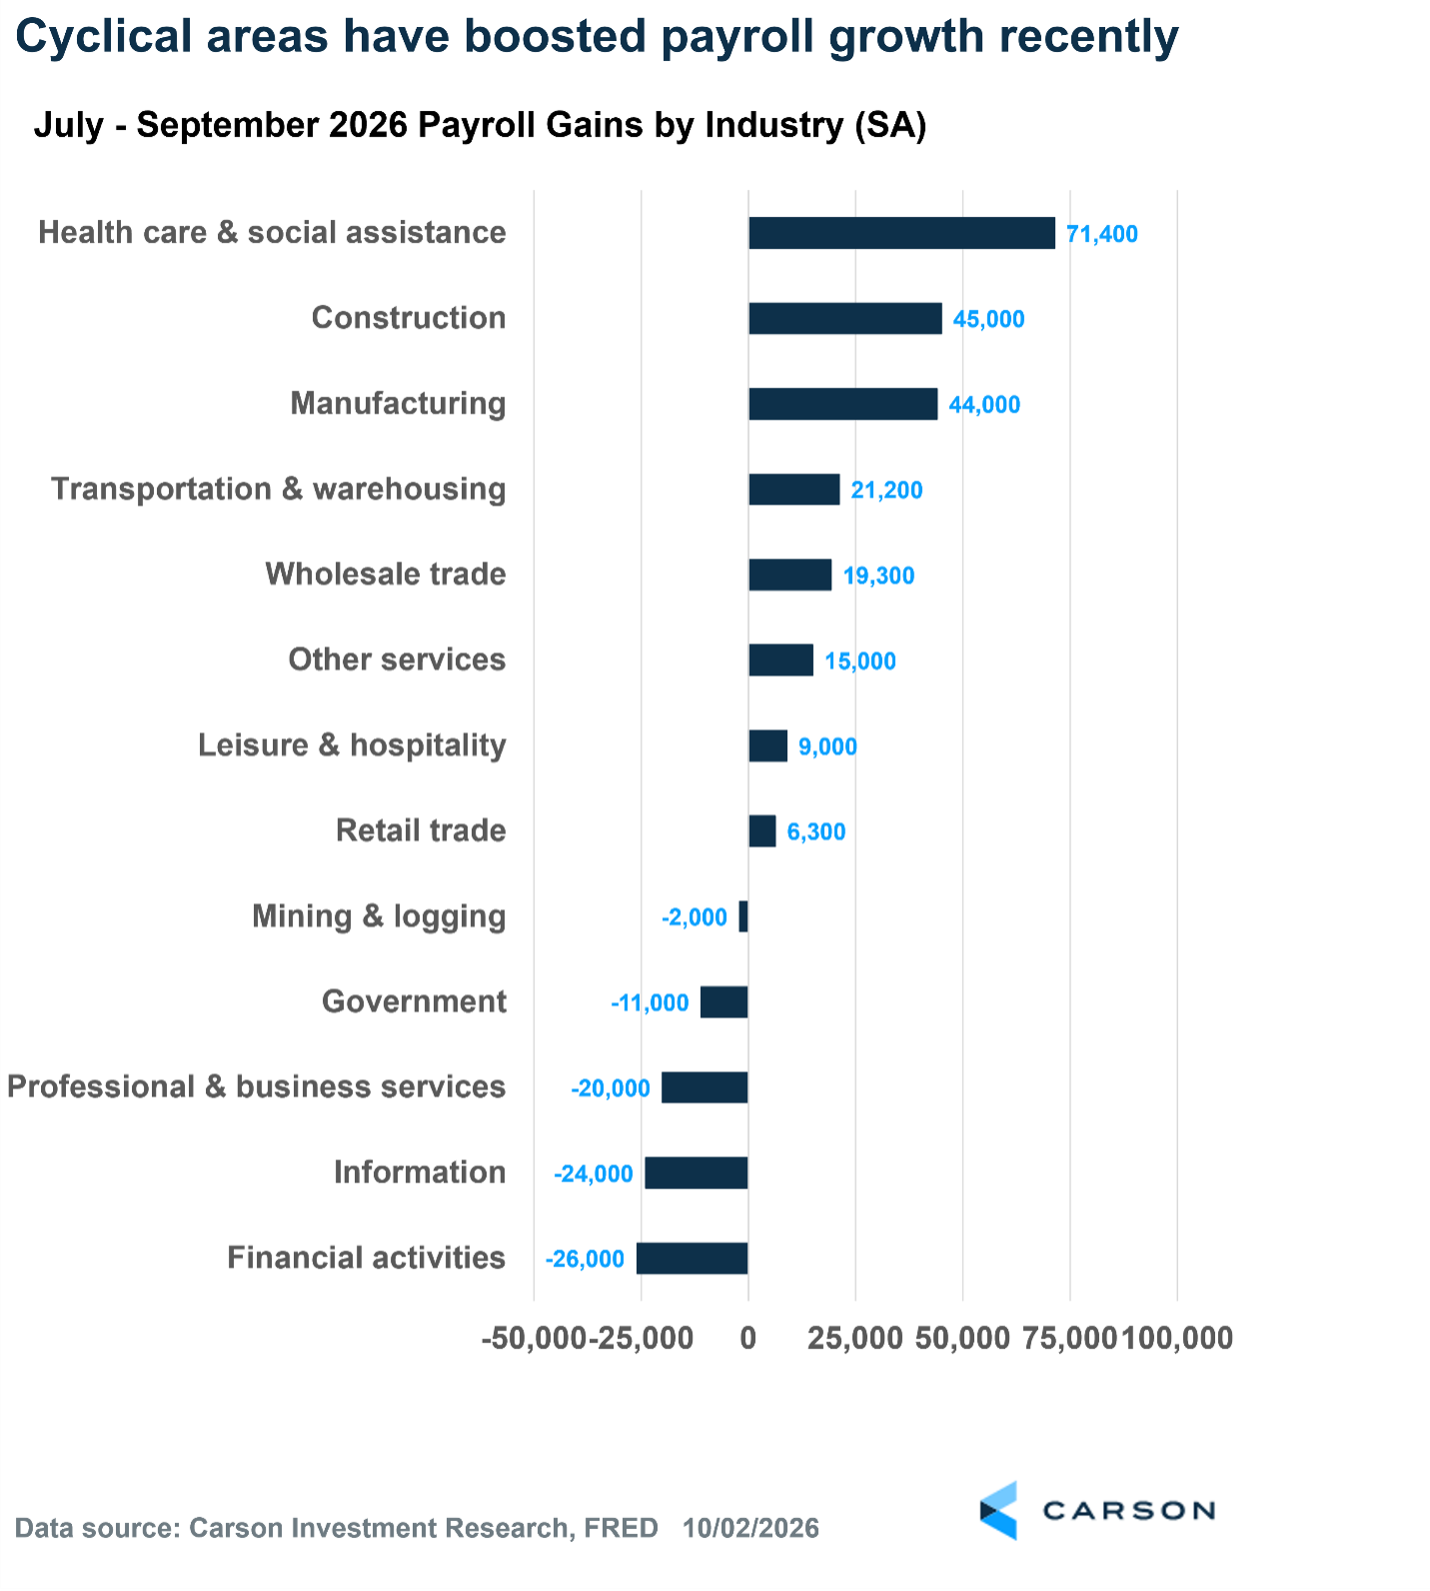
Under the hood, healthcare continues to do much of the heavy lifting, accounting for 71,000 of the 163,000 private-sector jobs added over the last three months. Construction (+45,000) and manufacturing (+44,000) are also adding jobs, likely helped by data center construction and AI-related investment. Financial activities and information continue to shed jobs, and professional and business services have cooled as well.
So we’d set aside the volatile payroll data, which only muddies the labor market picture, and focus on more stable metrics that don’t tend to get revised.
The labor market is quite solid
The unemployment rate rose from 4.14% to 4.18% in September, a much smaller change than the move from 4.1% to 4.2% rounded would suggest. 4.18% is still historically quite low, as it has been for a while. In fact, the unemployment rate has now been at 4.5% or below for a record 60 consecutive months, or five full years.
Even better, the prime-age (25-54) employment-population ratio jumped from 80.4% to 80.7%. We like this measure because it cuts through a lot of the noise in the unemployment rate around demographics and who counts as unemployed. The ratio is now higher than at any point in the 2000s or 2010s expansions, including 2018-19, when the labor market was strong. And it’s only a bit below the 80.9% peak for this cycle.
Layoffs also remain low. Initial jobless claims are near historical lows, coming in at just 197,000 in the latest week. Continuing claims are running about 10% below last year, which suggests it’s getting a tad easier for unemployed workers to find a job.
The Fed is willing to wait
Ultimately, the labor market is quite solid, so the Fed’s focus will remain on inflation. But recent comments from Fed officials suggest they’re willing to wait it out a bit longer. Even the more hawkish officials don’t seem inclined to do more than reverse last year’s “insurance cuts” of 0.75 percentage points.
That’s why the odds of an October rate hike fell from 70% earlier last week to just 20% after the report. Markets have also pulled back on hikes for the rest of the year. Earlier last week, futures were pricing in 150% odds of a rate hike (100% odds of one hike and 50% odds of a second). That’s now down to 95%. In other words, only one more hike is priced in for this year now.
Markets are treating this as a “bad news is good news” report, but this is about as good a version of bad news as you can get. That really makes it a Goldilocks report for markets. The immediate relief will be a stop to the surge in yields as markets price in an easier Fed. The 10-year Treasury yield, which hit 5.34% earlier last week (the highest in more than two decades), fell to around 5.2% after the report. That should also boost stocks. But the inflation problem remains, and the question is how long the Fed will let things run hot.
Inflation remains a problem, no matter how you slice and dice the data
The latest read on the Fed’s preferred inflation metric, the Personal Consumption Expenditures Price Index (PCE), was an important release because the Bureau of Economic Analysis revised its PCE methodology. Most notably, it replaced market-price-sensitive measures for portfolio management services with an employment-based approach that better captures the underlying quantity of services provided, instead of tracking stock prices. Price measures for legal services and computer software and accessories were also revised. The changes were retroactive to 2021 and revised inflation meaningfully lower, with July headline and core inflation each cut about 0.3 percentage points year over year, from 3.7% to 3.4% and 3.3% to 3.0%, respectively. There’s no real conspiracy here, and as we’ll see, inflation’s hot no matter how you slice and dice the data.
The latest PCE data is as of August, so it doesn’t reflect the recent surge in gasoline and diesel prices. We’ll have to wait another month for that. Still, headline PCE rose 0.3% in August (3.8% annualized) and is up 3.4% from a year ago. Core PCE, the Fed’s preferred gauge of underlying inflation, was hot too, rising 0.25% in August (3.0% annualized) and 3.0% over the past year. The six-month annualized pace is 2.7%.
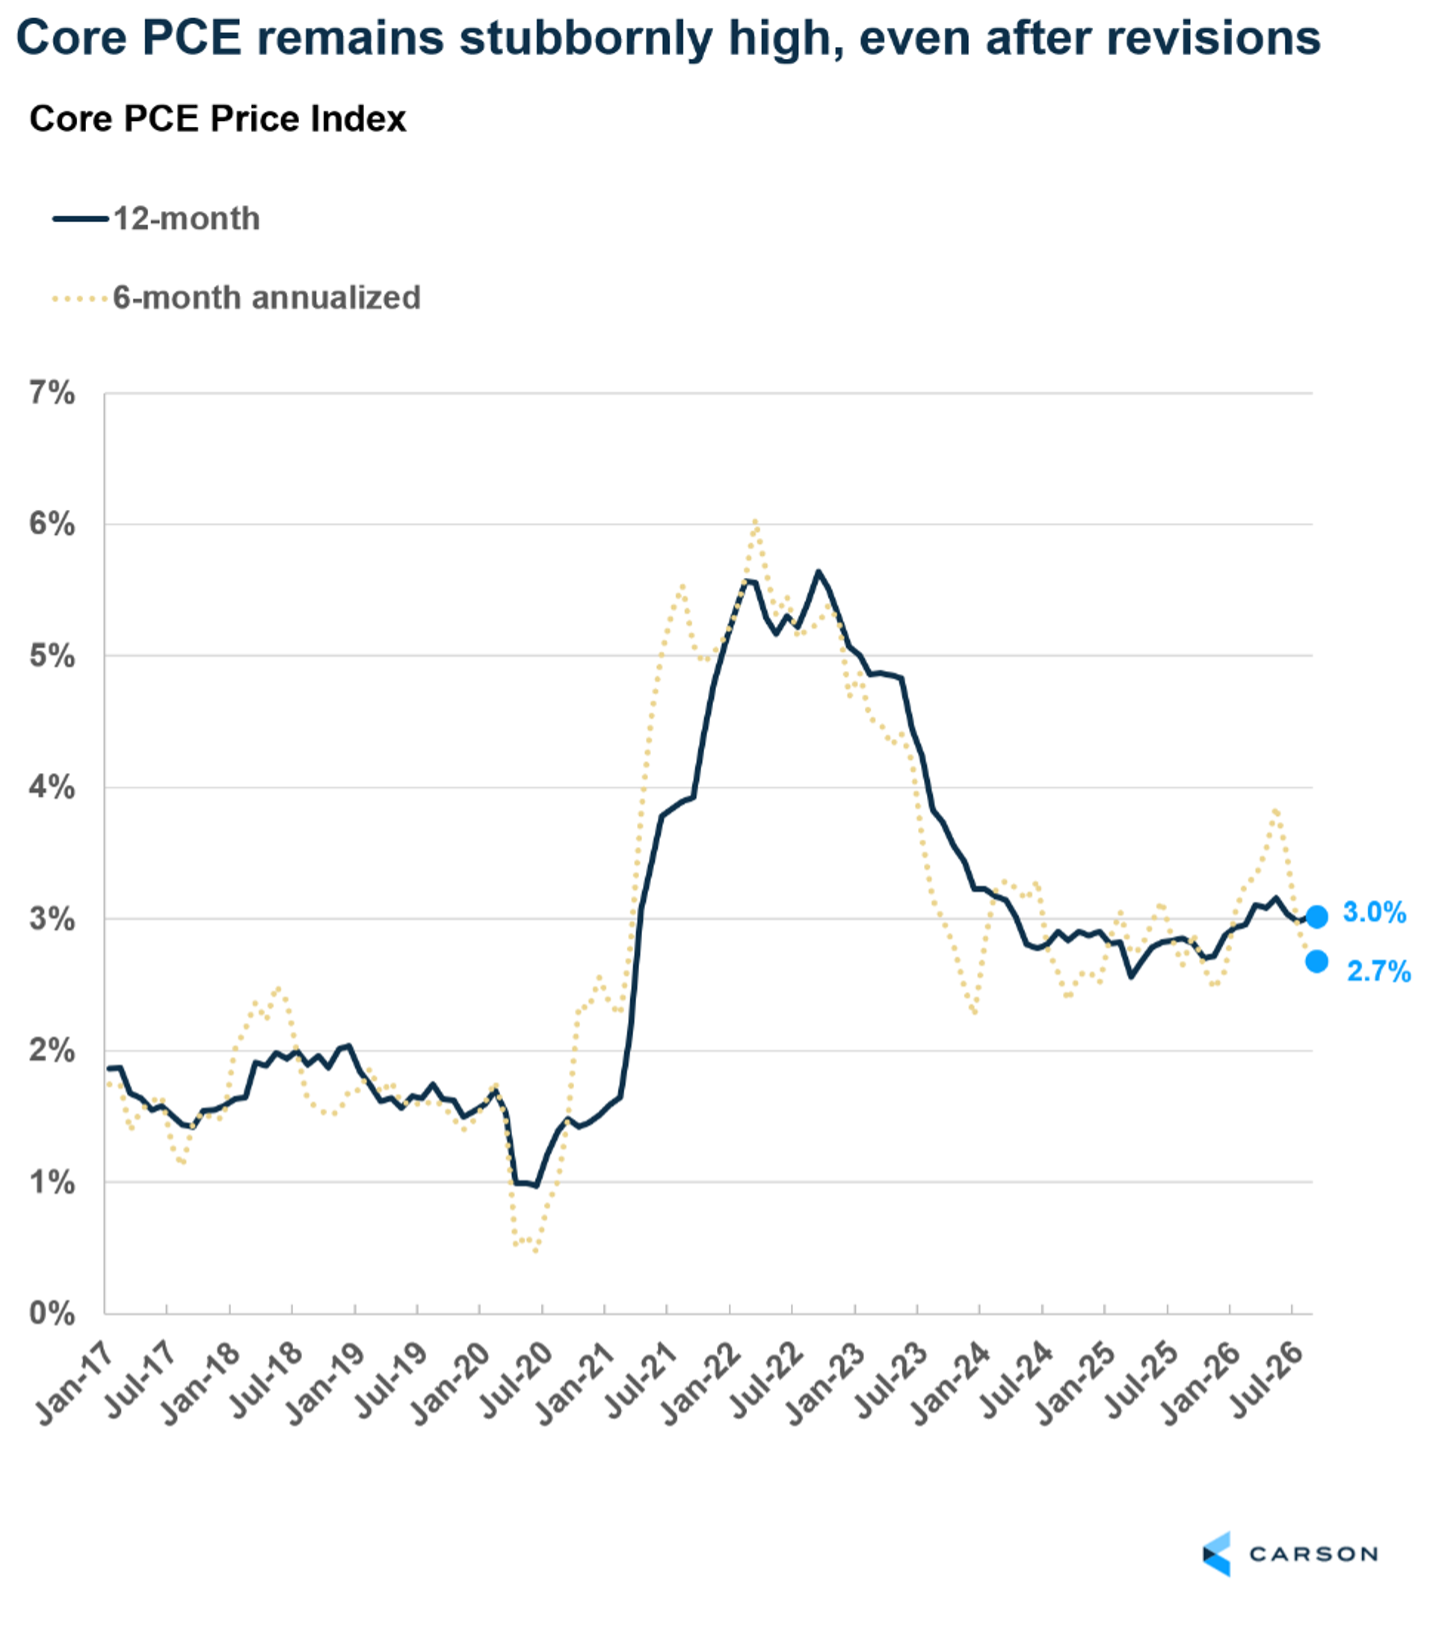
It’s obvious inflation’s running hot, but there’s plenty of confusion because core Consumer Price Index (CPI) inflation is softer than core PCE. Core CPI is up just 2.4% from a year ago and usually gets more headlines, even though the Fed has used PCE as its inflation gauge since 2000. PCE is broader, accounts for substitution as spending habits change, and allows older data to be revised. Another big difference is shelter, which is 42% of core CPI versus only 17% of core PCE.
Strip out the usual suspects, and inflation is still hot
One knock against these elevated PCE readings is that tariff-impacted goods inflation and elevated computer software inflation are pushing core PCE higher. The argument is that tariff inflation should fade and computer software prices weren’t being measured correctly. The latter was addressed in the methodology update. We’d argue tariffs don’t hit all at once, as companies pass higher import duties to consumers over time, making the impact more persistent. And the AI capex boom itself is inflationary, so focusing on the exact approach to measuring software prices misses the forest for the trees. Even if you exclude these, along with energy, food, and housing, inflation remains elevated. Core services excluding housing rose at a 4.4% annualized pace in August, is up 3.2% annualized over the past six months, and is up 3.5% over the past year. For comparison, here’s how it ran during the meat of the last three expansion cycles (all annualized):
- 1995-99: 2.5%
- 2003-07: 3.4%
- 2017-19: 2.2% (2010-19: 2.1%)
The current pace is well above what we saw previously (except for 2003-07, which we’ll get to below).
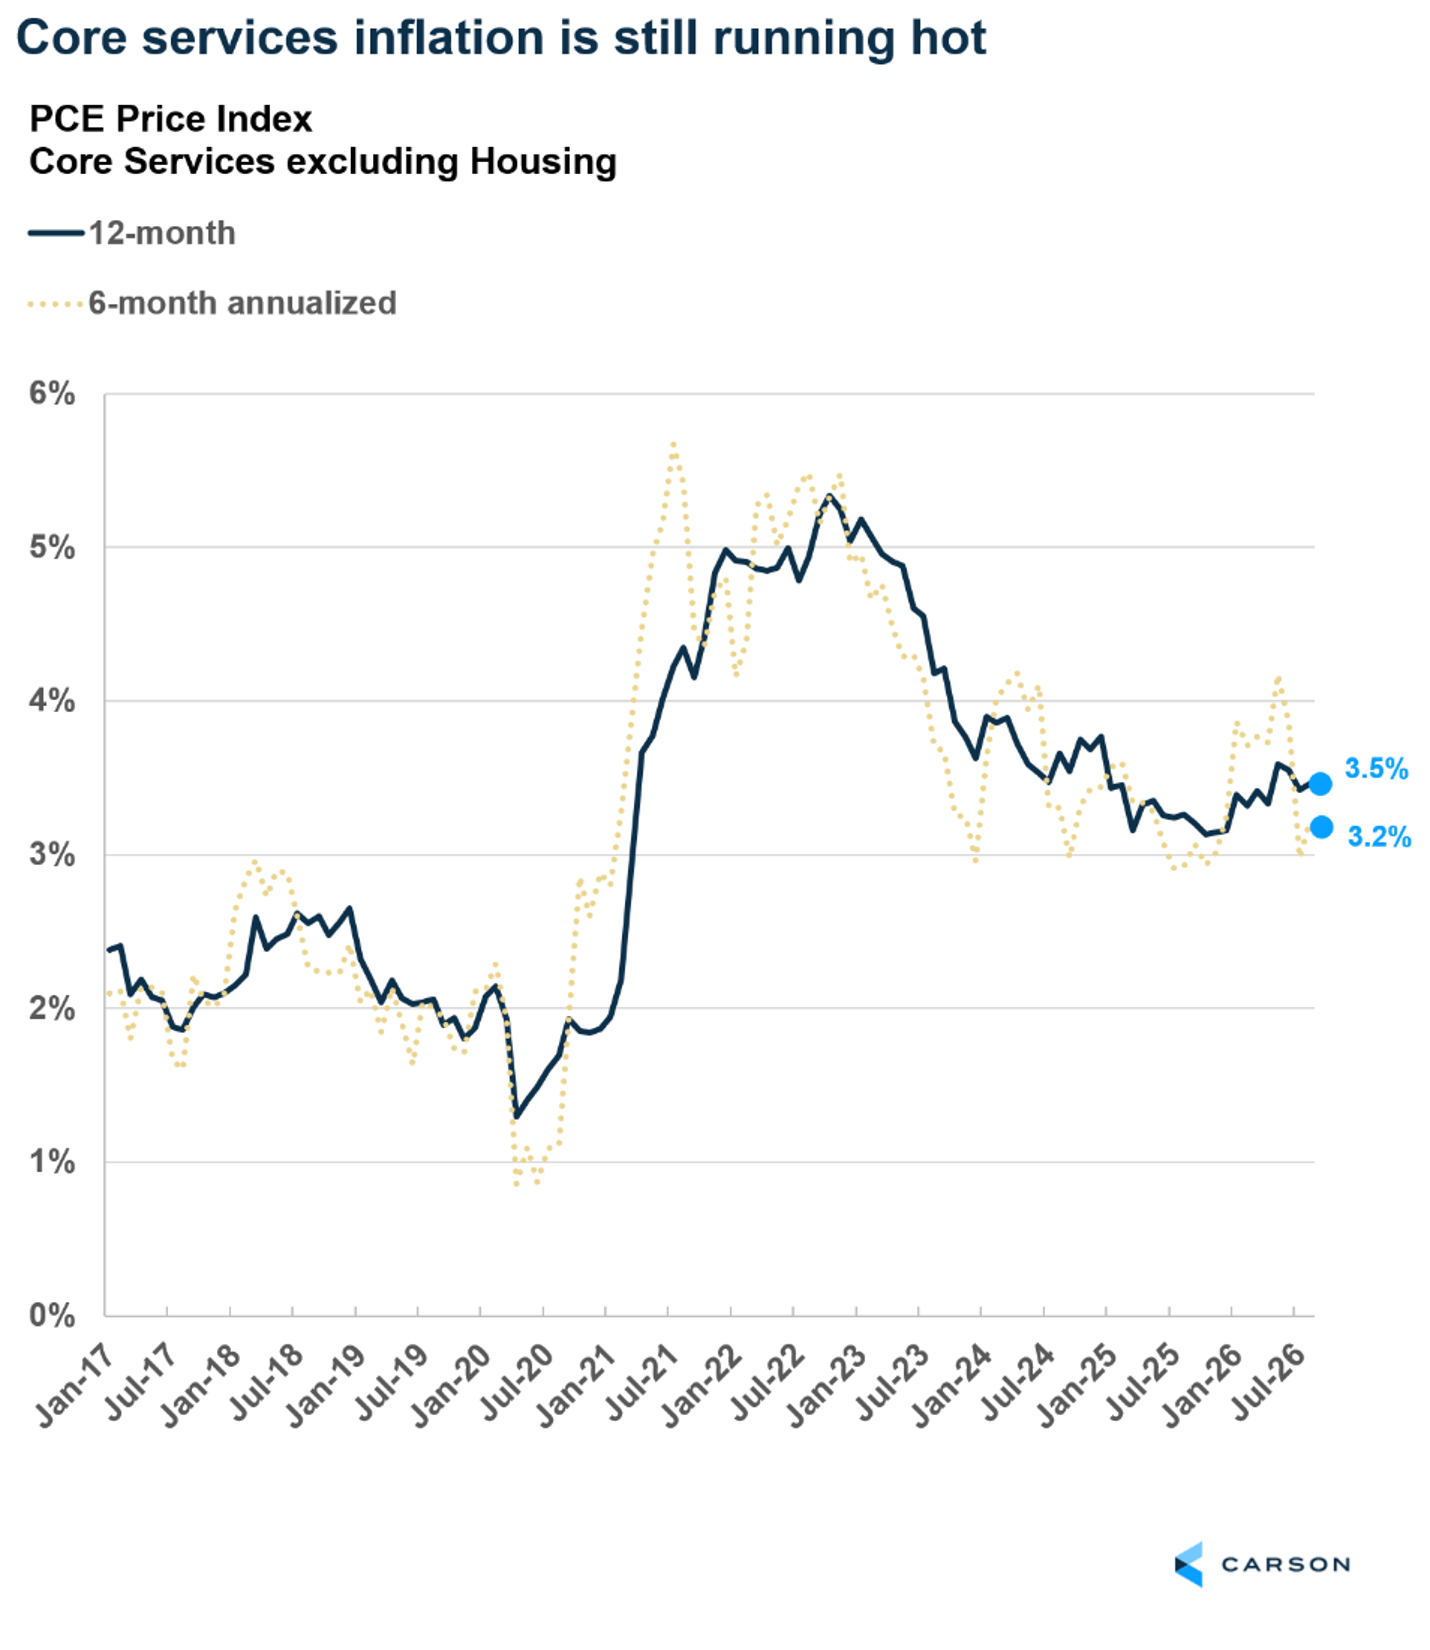
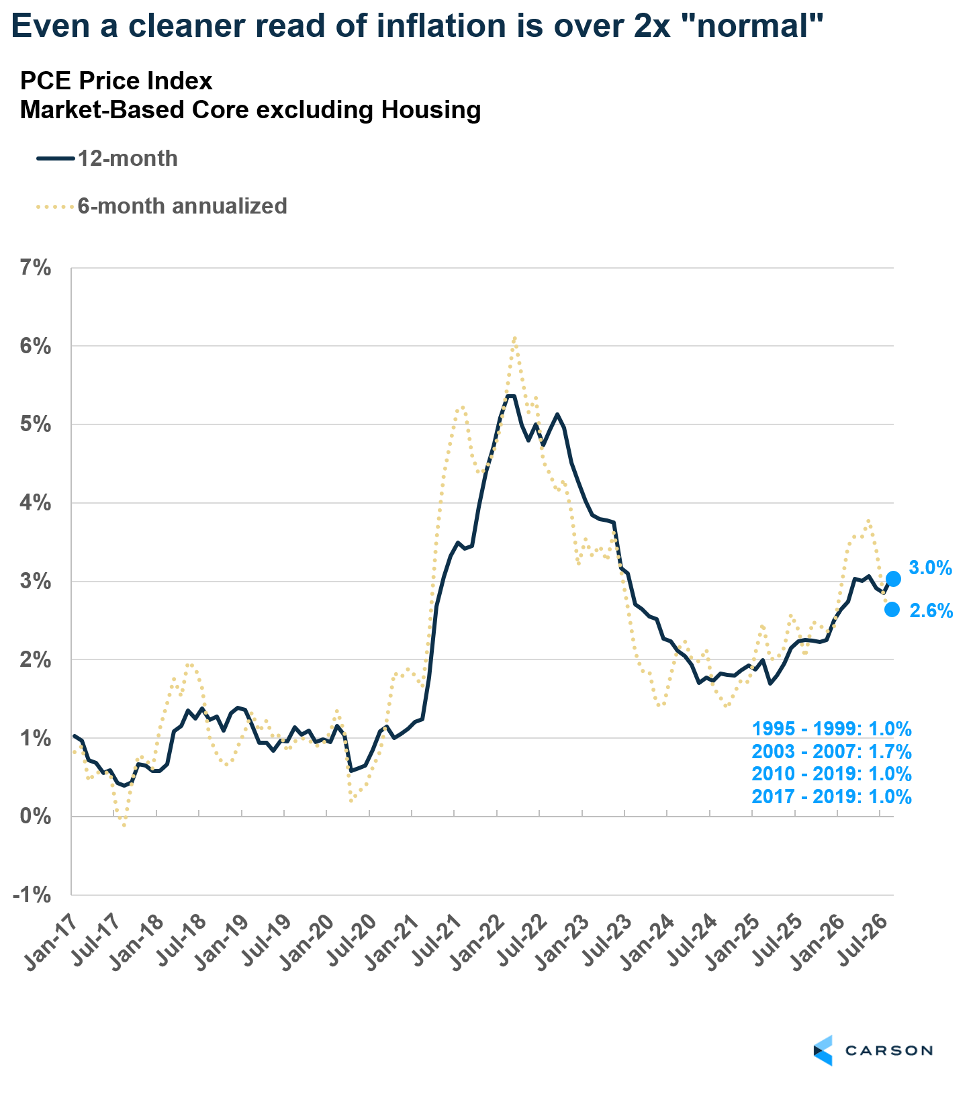
Some would argue even this cut isn’t right because several prices aren’t observed in ordinary transactions between businesses and consumers. That’s where “market-based” PCE comes in. It strips out components whose prices aren’t directly observed in market transactions. Market-based core services ex housing is up 2.6% annualized over the past six months and 3.0% over the past year. Here’s how this measure ran during prior expansions:
- 1995-99: 1.0%
- 2003-07: 1.7%
- 2017-19: 1.0% (2010-2019: 1.0%)
Suffice to say, we’re nowhere close to “normal,” with the current pace more than twice as fast as what we’ve seen in the past.
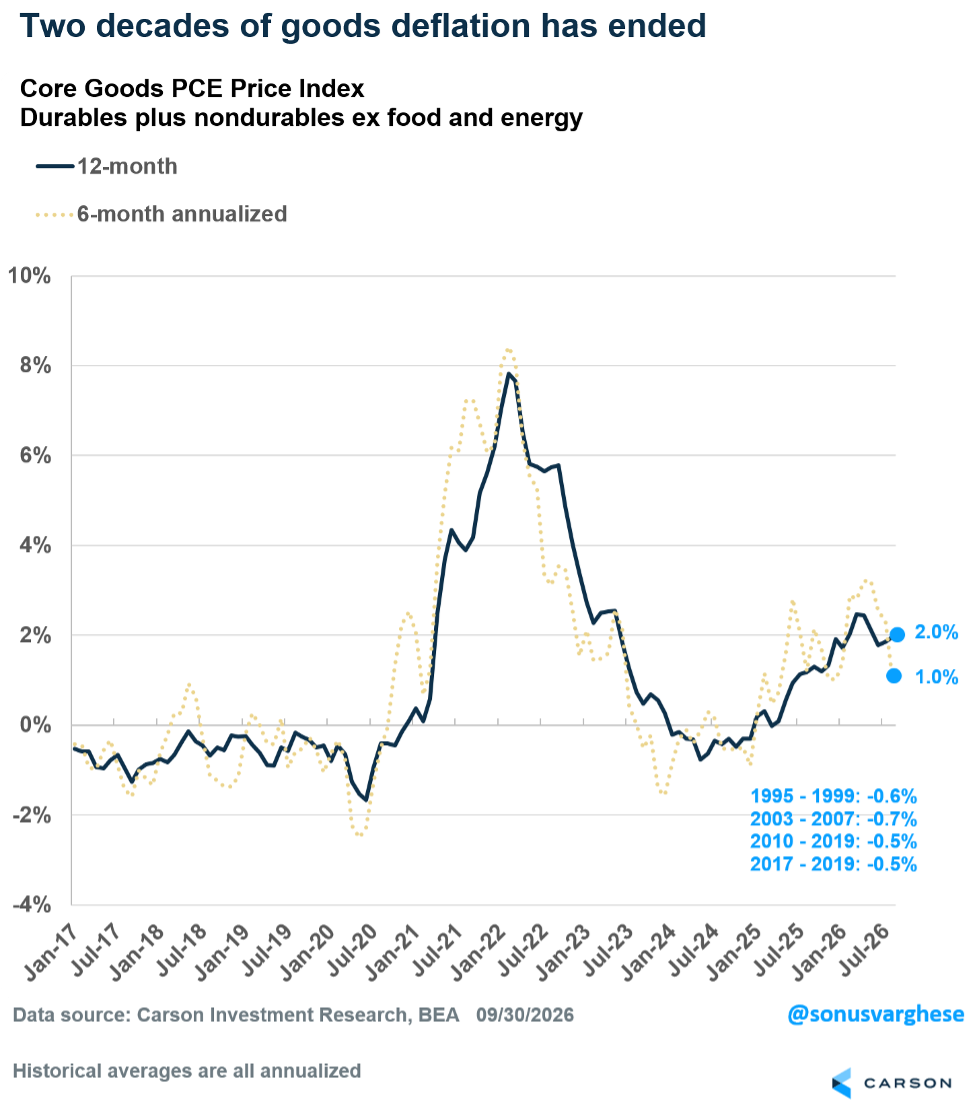
It would be one thing if core services were running hot while core goods prices were falling, as they were over the 25 years before 2021. That’s why core PCE averaged 2.1% annualized from 2003-07 despite core services ex housing running at 3.4%. Core goods inflation was -0.7%, providing an offset. That’s not the case today, thanks to tariffs and AI-related bottlenecks. Core goods PCE is up 1% annualized over the past six months and 2% over the past year. That may not sound like much, but it’s a big shift from a long-term deflationary environment where goods prices were actually falling and provides no offset to elevated services inflation.
Breadth of inflation still concerning
Beyond aggregate inflation data, it’s useful to look at the distribution of inflation across components. We looked at 178 items within the core PCE basket and calculated the distribution of year-over-year inflation at four points in time. Inflation broadened dramatically by June 2022 relative to December 2019. It narrowed through last year, but never fully normalized, and over the past year things have worsened again. That breadth matters because it tells us whether the problem is isolated or widespread. Here’s the proportion of items with inflation above 3% (above 4% in parentheses):
- December 2019: 24% with 3%+ inflation (10% with 4%+ inflation)
- June 2022: 72% (58%)
- August 2025: 48% (28%)
- August 2026: 52% (30%)
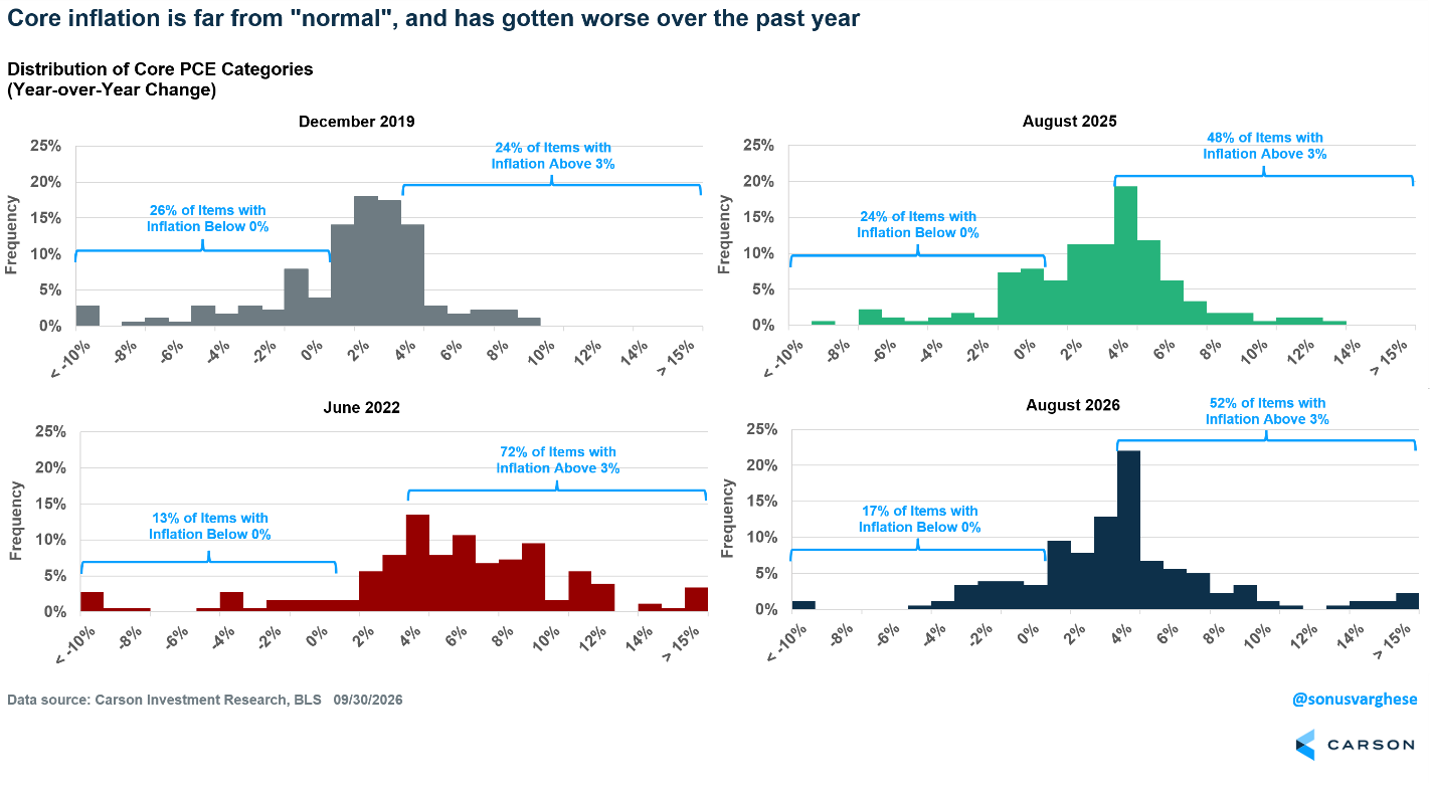
Fed Chair Kevin Warsh also cited this breadth data in his Jackson Hole speech in August, describing price pressures as widespread rather than isolated to a few categories.
Looking at this “diffusion index” back to 1995, the current 52% share of core PCE items with inflation above 3% is above the peak levels seen in prior cycles, and well above the historical averages shown in the chart. In other words, the current inflation problem is not just a handful of outliers.
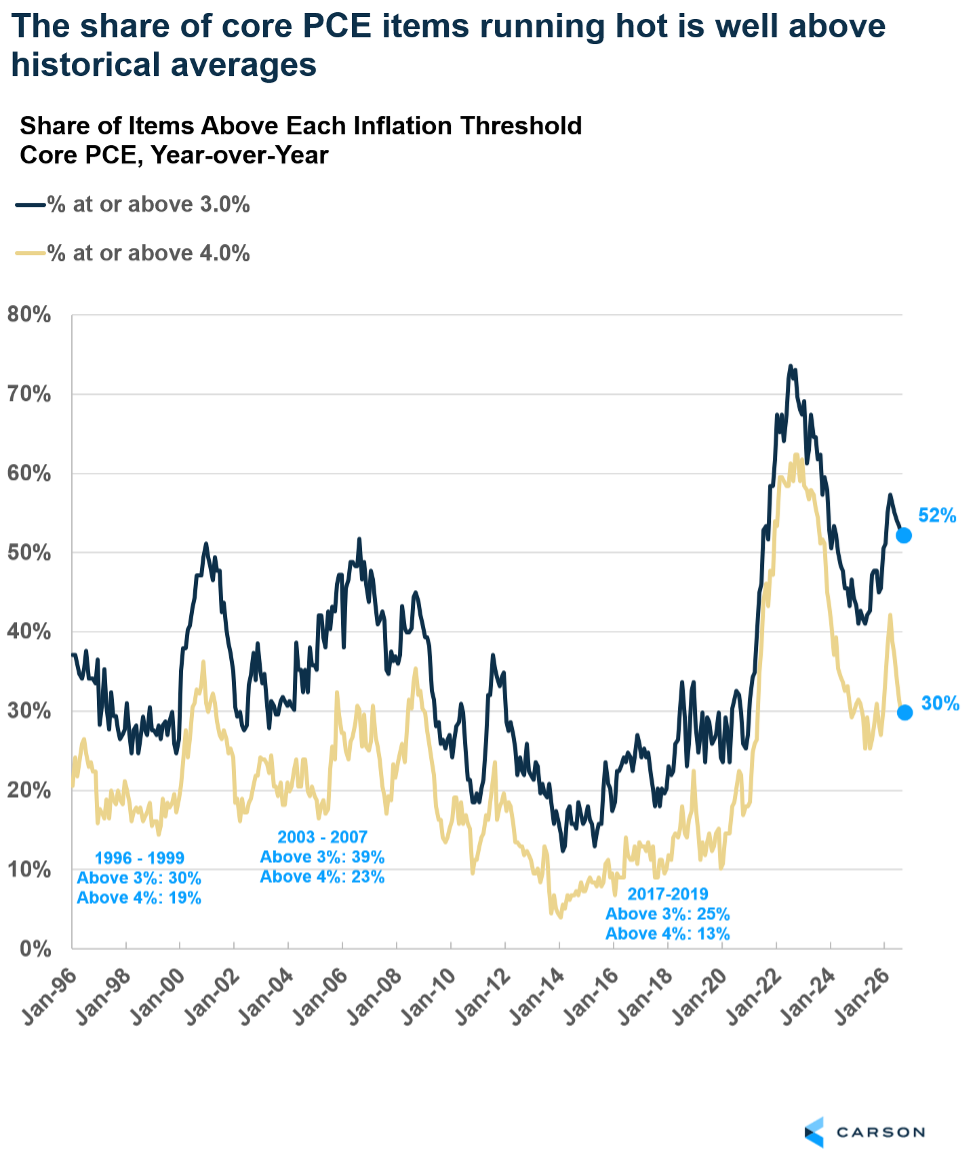
Things don’t look much better within core services ex housing. As of August, 58% of items are running above 3% year-over-year inflation and 33% above 4%. Here’s how that compares with history:
- 1996-99: 41% above 3% (27% above 4%)
- 2003-07: 55% above 3% (32% above 4%)
- 2017-19: 29% above 3% (17% above 4%)
Hot growth is good news for stocks, for now
There’s no two ways about it. Slice the data any way you want, and it still shows an inflation problem. The question is how far the Fed is willing to go to pull it back as we move into the fourth quarter and 2027. With the labor market strengthening and non-residential capex spending running gangbusters on the back of the AI boom, it’s hard to see inflation easing meaningfully without a bust. But that’s not really on the cards right now.
Recent revisions to second-quarter GDP data showed real GDP growth revised up from 1.5% to 2.2%. That doesn’t seem very exciting, but nominal GDP growth, which is what matters for company revenues and profits, was revised up from 8.0% to 8.5%. The third quarter seems set to run just as hot. For now, all this is good news for the stock market.
S&P 500 — A capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.
The NASDAQ 100 Index is a stock index of the 100 largest companies by market capitalization traded on NASDAQ Stock Market. The NASDAQ 100 Index includes publicly traded companies from most sectors in the global economy, the major exception being financial services.
The views stated in this letter are not necessarily the opinion of Cetera Wealth Services LLC and should not be construed directly or indirectly as an offer to buy or sell any securities mentioned herein. Investors cannot invest directly in indexes. The performance of any index is not indicative of the performance of any investment and does not take into account the effects of inflation and the fees and expenses associated with investing.
A diversified portfolio does not assure a profit or protect against loss in a declining market.
All investing involves risk, including the possible loss of principal. There is no assurance that any investment strategy will be successful. This information is from sources believed to be reliable, but Cetera Wealth Services, LLC cannot guarantee or represent that it is accurate or complete.
9161464.1-1026-C
